
|
|
|
| A way of thinking about the role of the |
||
| inverse covariance matrix |
||
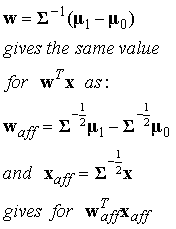
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| • | If the Gaussian
is spherical we |
||||||||||||||||||
| don’t need to
worry about the |
|||||||||||||||||||
| covariance
matrix. |
|||||||||||||||||||
| • | So we could start
by |
||||||||||||||||||
| transforming the
data space to |
|||||||||||||||||||
| make the
Gaussian spherical |
|||||||||||||||||||
| – | This
is called “whitening” |
||||||||||||||||||
| the
data. |
|||||||||||||||||||
| – | It
pre-multiplies by the |
||||||||||||||||||
| matrix
square root of the |
|||||||||||||||||||
| inverse
covariance matrix. |
|||||||||||||||||||
| • | In the
transformed space, the |
||||||||||||||||||
| weight vector is
just the |
|||||||||||||||||||
| difference
between the |
|||||||||||||||||||
| transformed
means. |
|||||||||||||||||||